
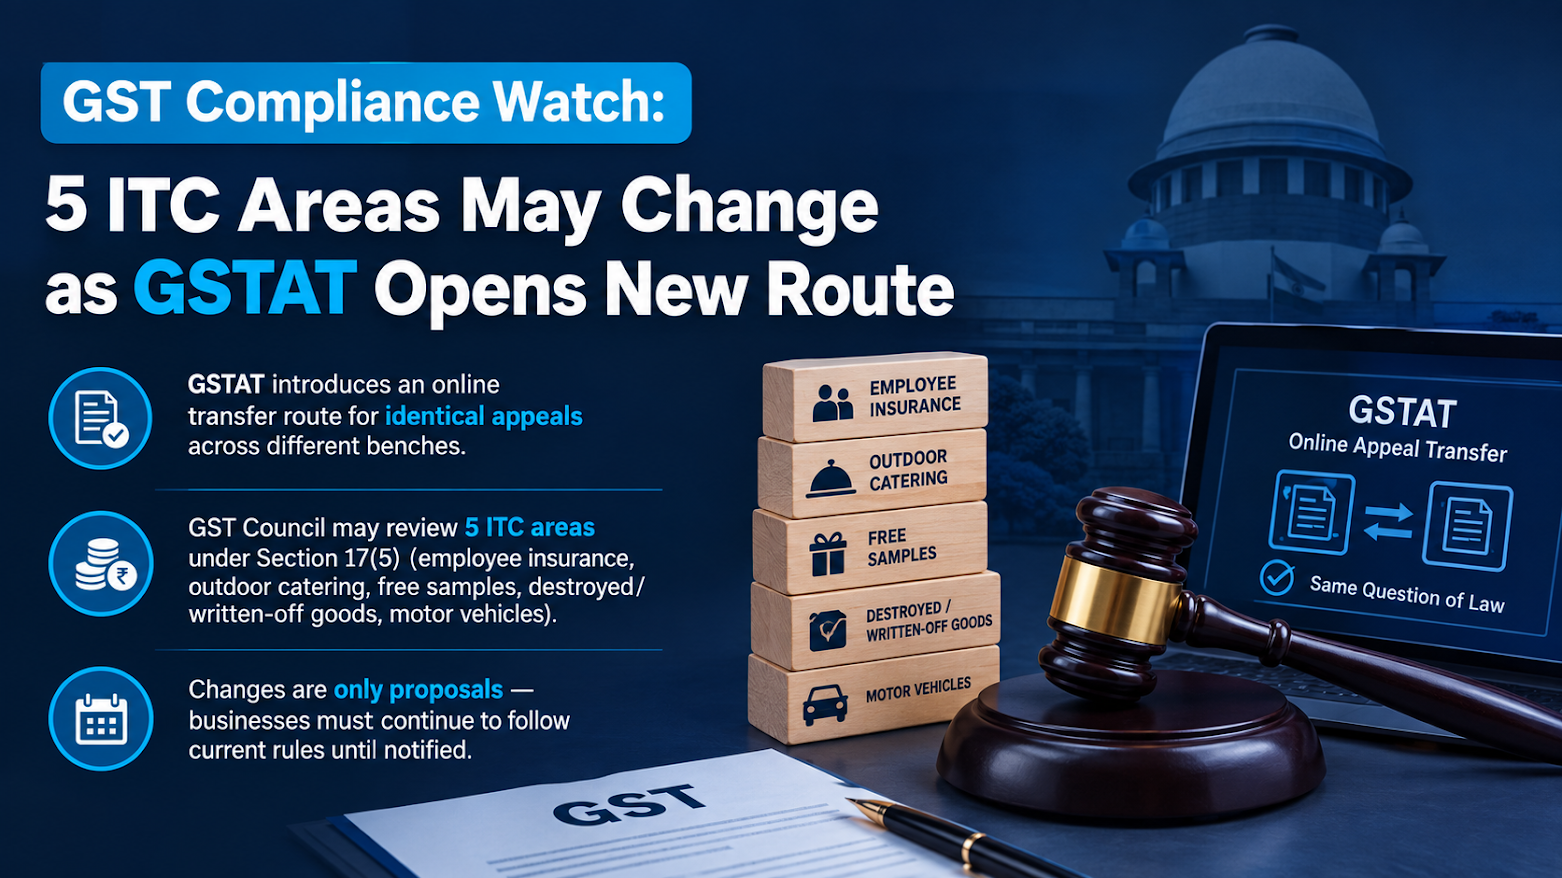
Overview: Businesses handling GST litigation and blocked Input Tax Credit (ITC) are watching two developments closely. Goods and Services Tax Appellate Tribunal (GSTAT) has introduced an online mechanism for taxpayers seeking transfer of appeals involving an identical question of law across different benches. Separately, the GST Council may consider five areas linked to blocked Input Tax Credit (ITC) under Section 17(5), covering employee insurance, outdoor catering, free samples, specified destroyed or written-off goods, and motor vehicles.
Introduction
The Goods and Services Appellate Tribunal (GSTAT) has introduced an online route that allows eligible taxpayers with multiple GSTINs linked to one PAN to seek transfer of appeals involving the same question of law. According to a report by the Mint, 504 appeals across nine State Benches had been identified on the issue of whether delay can be condoned beyond the limit prescribed under Section 107(4) of the CGST Act.
The cases were spread across Hyderabad, Bhopal, Kolkata, Chennai, Raipur, Guwahati, Ranchi, Vijayawada and Dehradun.
At the same time, the GST Council is expected to examine proposed changes to blocked ITC at its October 7, 2026 meeting. The Law Committee has reportedly supported relief in four areas, while the proposal relating to motor vehicles and their leasing, renting or hiring remains for the GST Council to consider. Businesses should treat these as proposals until the relevant legal amendments take effect.
Five ITC Areas Under Review
Section 17(5) of the CGST Act currently restricts ITC for several specified goods and services, subject to prescribed exceptions. The reported proposals would reconsider restrictions in five areas.
| Area | Reported position |
|---|---|
| Employee life and health insurance | Law Committee has reportedly supported relief for qualifying employee/group insurance policies |
| Outdoor catering | Relief proposed for qualifying business-related expenditure |
| Free samples | Proposal to remove the existing blocking restriction |
| Goods destroyed or written off | Relief proposed in specified cases, including goods required to be destroyed under law |
| Motor vehicles, leasing, renting or hiring | No consensus reported; issue left for the GST Council |
The reported proposals are not yet changes in the law. Until an amendment is approved, notified and made effective, businesses must continue to apply the existing Section 17(5) provisions.
What the ITC Proposals Could Mean for Businesses
The proposals are relevant to businesses whose regular expenses fall within the existing blocked-credit provisions.
Companies providing employee group insurance, businesses incurring outdoor catering expenses for qualifying business activities, and sectors that distribute free product samples could be affected if the proposed changes are implemented.
The proposal concerning goods destroyed or written off is also relevant to businesses dealing with expiry, shelf-life restrictions or other legally required destruction of goods. Under the current law, Section 17(5)(h) covers goods that are lost, stolen, destroyed, written off or disposed of by way of gift or free samples.
Motor vehicles remain a separate issue because Section 17(5) contains specific restrictions and exceptions relating to vehicles and related services. The reported Law Committee position does not settle this issue; the GST Council is expected to consider it.
Businesses should therefore not treat the reported proposals as available ITC. Any change will require the relevant legal amendment and its effective date.
GSTAT Online Transfer Route for Identical Appeals
The second development concerns GST litigation.
GSTAT’s online system now provides a route for taxpayers to seek transfer of appeals involving an identical question of law pending before different benches. The facility is particularly relevant where multiple GSTINs under the same PAN have separate appeals involving the same legal issue.
The development follows GSTAT’s identification of 504 appeals across nine State Benches involving the question of whether the statutory limit for condoning delay under Section 107(4) can be extended beyond the prescribed outer limit.
For businesses operating across several States, the facility makes it important to maintain a consolidated record of GSTIN-wise appeals, disputed issues, orders, filing dates and limitation periods.
Watch
What Businesses Should Do
- Review blocked ITC connected with the five areas under discussion.
- Maintain invoices and supporting evidence for business expenditure.
- Keep business and personal expenditure clearly separated.
- Do not claim additional ITC based only on a reported proposal.
- Track notifications and effective dates if Section 17(5) is amended.
- Multi-State businesses should identify identical GST disputes across GSTINs and maintain a central litigation tracker.
- Keep appeal orders, filing records and limitation dates properly documented.
Setindiabiz Support
Setindiabiz supports businesses with GST compliance, ITC review and multi-State GST litigation documentation. This includes reviewing blocked-credit positions, reconciling supporting records and tracking GST disputes across multiple GSTINs.
For businesses with common GST disputes in different States, our compliance team can help organise GSTIN-wise appeal records, orders, filing details and supporting documentation relevant to the GSTAT process. Our team also tracks changes in GST law and help businesses assess the compliance impact of amendments once they are formally notified and become effective.
FAQs
What is the new GSTAT transfer mechanism?
GSTAT has introduced an online process through which eligible taxpayers can seek transfer of appeals involving an identical question of law pending before different benches. The facility is particularly relevant to businesses with multiple GSTINs linked to the same PAN.
What are the five ITC areas being considered for relief?
The reported agenda covers employee life and health insurance, outdoor catering, free samples, specified goods destroyed or written off, and motor vehicles along with their leasing, renting or hiring. The Law Committee has reportedly supported relief in four areas, while the motor-vehicle issue remains for the GST Council to consider.
Can businesses claim ITC on these items immediately?
No. Businesses should continue following the existing Section 17(5) provisions until any amendment is formally approved, notified and made effective. ITC should not be claimed merely because a change has been proposed.
The GSTAT transfer facility is an immediate procedural development, while the five ITC proposals remain subject to the GST Council’s decision and subsequent legal implementation. Businesses should therefore focus on litigation tracking, ITC documentation and monitoring of notified changes rather than changing their credit positions based only on reported proposals.
For businesses operating across multiple States, maintaining a clear GSTIN-wise record of ITC positions, disputes, appeal orders and filing dates can also make it easier to respond when GST litigation or compliance requirements change.
In This Article
Author Bio

Setindiabiz Editorial Team is a multidisciplinary collective of Chartered Accountants, Company Secretaries, and Advocates offering authoritative insights on India’s regulatory and business landscape. With decades of experience in compliance, taxation, and advisory, they empower entrepreneurs and enterprises to make informed decisions.
