
Limited Liability Partnership (LLP) Registration Online in India
LLP registration gives two or more partners a separate legal entity with limited liability under the Limited Liability Partnership Act, 2008. Setindiabiz files RUN-LLP and FiLLiP online, then drafts and files the LLP agreement in Form 3; incorporation usually takes 10–15 working days. There is no minimum capital, and NRIs and foreign nationals can be partners.
Trusted By Leading Brands

What is an LLP?
An LLP is a body corporate registered under the LLP Act, 2008: a legal entity separate from its partners, with perpetual succession (Section 3). Registration is one-time: there is no renewal, and the LLP continues until it is wound up or struck off. Partners are not personally liable for the LLP’s obligations merely by being partners (Section 28), and the LLP agreement sets out their rights and duties (Section 23). It is often searched as “LLP company registration”, but an LLP is not a company.
Setindiabiz’s process experts file RUN-LLP and FiLLiP on the MCA V3 portal, obtain the DPINs, PAN and TAN, and file the LLP agreement in Form 3 within 30 days. Everything is done online; no visit to the Registrar’s office is required.
Disclaimer: Setindiabiz is a private professional services firm and is not affiliated with any government body. We do not issue government documents. We assist you in preparing and filing the LLP incorporation application with the Ministry of Corporate Affairs (MCA). The Certificate of Incorporation, LLPIN, PAN and TAN are issued solely by the Government of India.
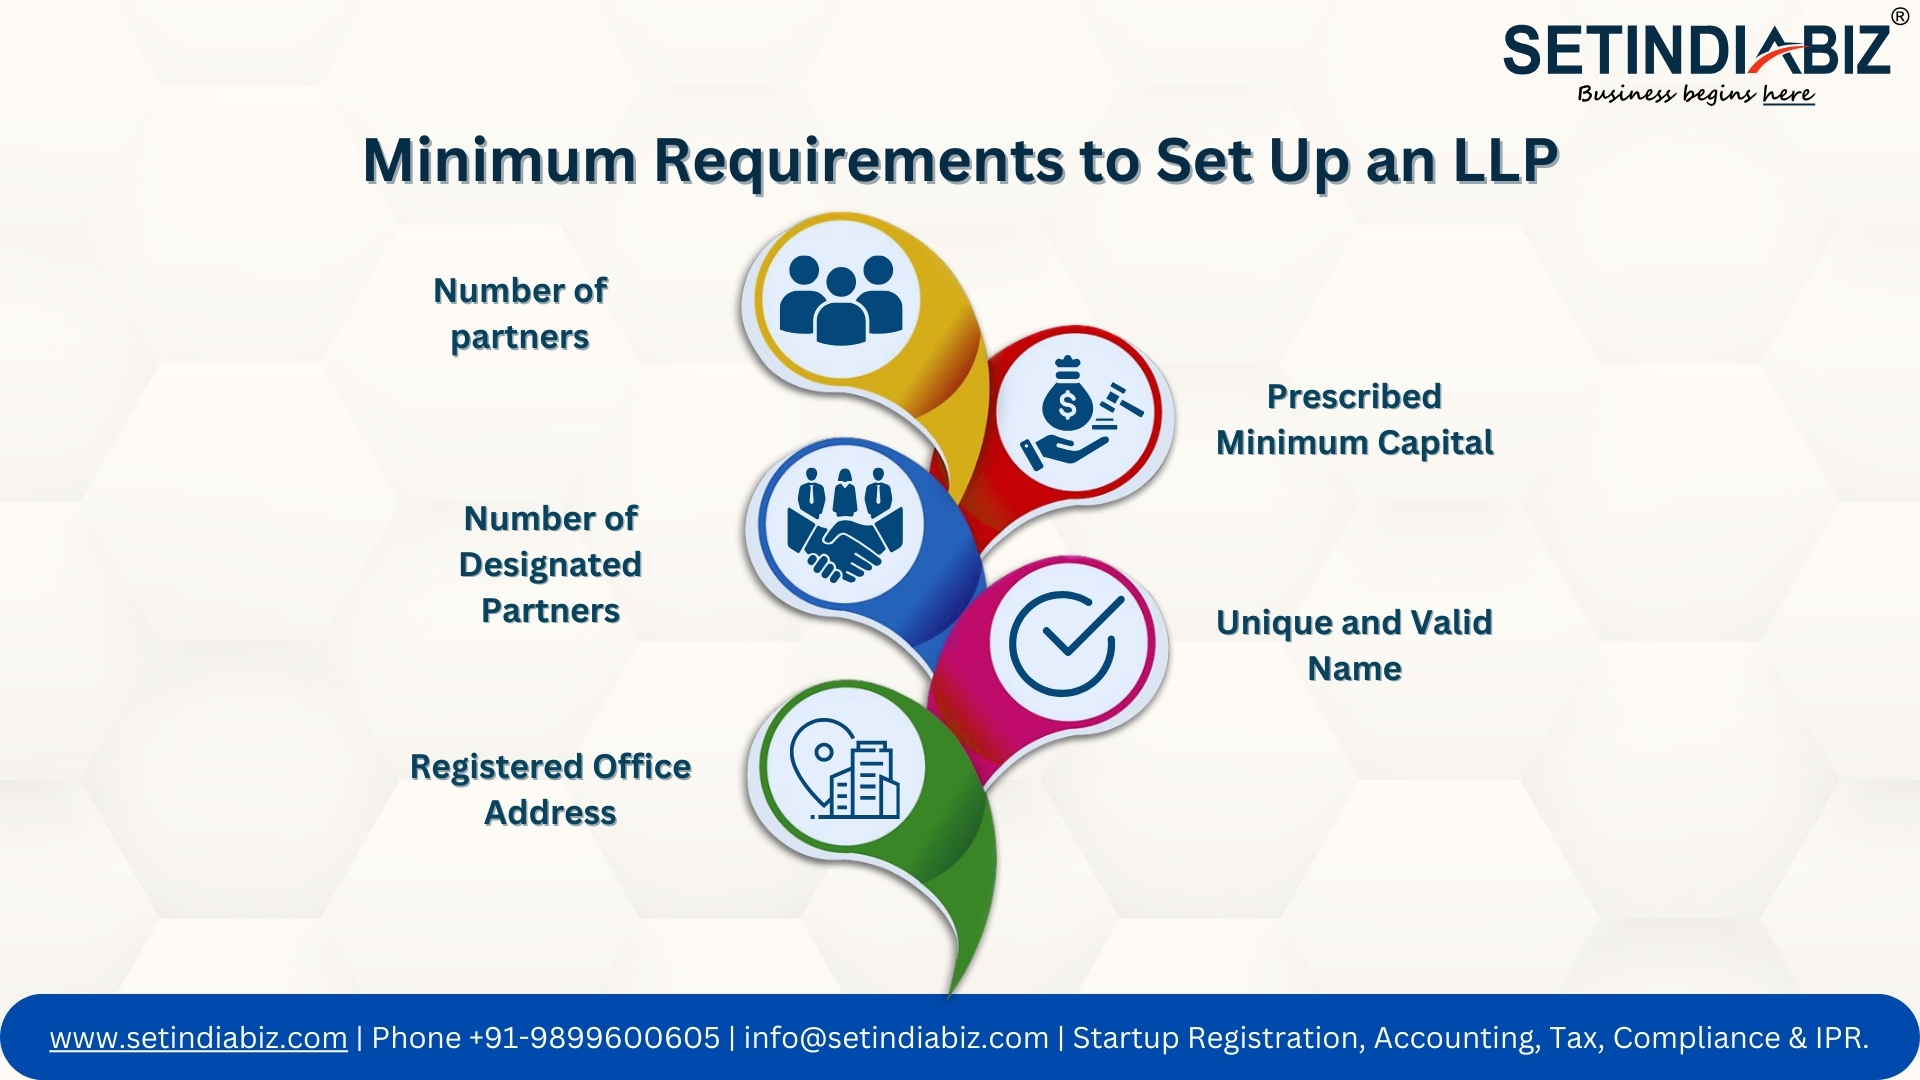
Minimum Requirements & Eligibility
-
At least two partners
Any individual or body corporate can be a partner, including a foreign national or a foreign company; there is no upper limit on the number of partners. If the LLP carries on business with a single partner for more than six months, that partner becomes personally liable for obligations incurred in that period, if they know they are the sole partner. Sections 5 and 6, LLP Act, 2008.
-
Two designated partners, one resident in India
At least two designated partners must be individuals, and at least one of them must be resident in India, that is, have stayed in India for at least 120 days during the financial year. Where a body corporate is a partner, it nominates an individual to act as designated partner. Section 7(1) of the LLP Act, 2008, as amended by the LLP (Amendment) Act, 2021.
-
DPIN and digital signature
Every designated partner needs a Designated Partner Identification Number (DPIN), or an existing DIN, and a Class 3 digital signature to sign the e-forms. FiLLiP allots DPINs to up to five new designated partners as part of the incorporation application. Section 7(6), LLP Act, 2008; Rules 10 and 11, LLP Rules, 2009.
-
No minimum capital or contribution
The Act prescribes no minimum capital. Partners agree on their contribution in the LLP agreement, and it may be cash, property, or services; a practising chartered accountant, cost accountant, or approved valuer values a non-cash contribution. The contribution slab decides the FiLLiP and Form 3 government fees. Section 32, LLP Act, 2008; Annexure A, LLP Rules, 2009.
-
A distinctive name ending in LLP
The name must not be identical or too similar to an existing LLP, company or registered trade mark, and it must end with “Limited Liability Partnership” or “LLP”. A name approved through RUN-LLP is reserved for three months. Sections 15 and 16, LLP Act, 2008; Rule 18, LLP Rules, 2009.
-
A registered office in India
Every LLP must have a registered office to which official communications can be sent. A residential address can be used. FiLLiP asks for the registered office address and its proof at filing; there is no 30-day window as for a company. A later change is filed in Form 15. Section 13, LLP Act, 2008; Rule 11 and Form FiLLiP, LLP Rules, 2009.
LLP Registration Cost
Our Pricing Promise
- Nothing Hidden
- Stamp Paper Bought by You
- Fully Customisable
- GST Shown Separately
- Transparent & Itemised
- Written Estimate by Email
- Govt Fee at Actuals
- Cited Exclusions (if any)
Why no open pricing? The cost depends on the partners’ contribution, your State and what you already hold. We send a written estimate before you pay; you buy the stamp paper and arrange any notarisation.
Incorporation Cost
For two partners with contribution up to ₹1 lakh, MCA fees are ₹750; DSCs and stamp duty are extra. Pricing Starts @
₹2,499/-
Prof Fee Only, Govt Fee and GST at actuals
Inclusions of this package
- Class 3 DSC for two designated partners (at actuals)
- Name search and RUN-LLP filing
- FiLLiP filing with DPIN allotment
- Certificate of Incorporation with LLPIN
- LLP PAN and TAN
- LLP agreement drafting and Form 3 filing
One fixed professional fee for a standard LLP incorporation with two individual designated partners resident in India. Government fees, DSC charges and stamp duty on the LLP agreement are billed at actuals, and GST is shown separately in the invoice.
LLP Registration
Fixed professional fee. Government fee, stamp duty and DSC charges at actuals; GST at 18% extra.
₹ 2,499
professional fee
Calculate All-Inclusive CostBasic ₹ 2,499/-
₹ 6,499 (Save ₹ 4,000)
For two partners who need the LLP incorporated and its agreement on record.
- DPIN for Two Designated Partners
- Name Search & Approval
- Certificate of Incorporation
- LLP PAN & TAN
- LLP Agreement Drafting
- Form 3 Filing
Silver ₹ 11,999/-
₹ 14,499 (Save ₹ 2,500)
For partners who will trade from day one and want the key registrations done with incorporation.
- Everything in the Basic Plan +
- GST Registration
- MSME (Udyam) Registration
- Shops Act Registration
- GST Returns for the First Year
Gold ₹ 18,999/-
₹ 22,499 (Save ₹ 3,500)
For partners who also want the first year’s MCA and income-tax filings handled.
- Everything in the Silver Plan +
- DPIN KYC (Up to 3 Partners)
- Annual Return (Form 11)
- Accounts & Solvency (Form 8)
- LLP Income-tax Return
Illustrative figures for design review only — not an offer.
| No. | What’s included | Basic ₹ 2,499 | Silver ₹ 11,999 | Gold ₹ 18,999 |
|---|---|---|---|---|
| 1 | DPIN & DSC for two designated partners Each designated partner needs a DPIN and a Class 3 digital signature to sign the e-forms. FiLLiP allots DPINs to up to five new designated partners, so no separate application is needed. A partner who already holds a DIN uses it. DSC charges are billed at actuals. | ✓ Yes | ✓ Yes | ✓ Yes |
| 2 | Name search & RUN-LLP We search the MCA records and the trade mark register for clashes, then file RUN-LLP with up to two proposed names and the ₹200 government fee. Once the Central Registration Centre approves a name, it is reserved for three months, and FiLLiP is filed within that time. | ✓ Yes | ✓ Yes | ✓ Yes |
| 3 | FiLLiP, Certificate of Incorporation, PAN & TAN FiLLiP is the single incorporation application, carrying the incorporation document, the partners’ details, their contribution and the office proof. The Registrar then issues the Certificate of Incorporation with the LLPIN, and it also carries the LLP’s PAN and TAN. | ✓ Yes | ✓ Yes | ✓ Yes |
| 4 | LLP agreement & Form 3 We draft the LLP agreement on contribution, profit sharing, duties and the admission or exit of partners. The partners sign it on stamp paper of the value fixed by their State, and we file it in Form 3 within 30 days of incorporation. Stamp duty is billed at actuals. | ✓ Yes | ✓ Yes | ✓ Yes |
| 5 | GST registration We file the GSTIN application in the LLP’s name. GST registration is needed once turnover crosses the threshold, or from the first inter-State supply of goods or sale through an e-commerce operator. An LLP can also register earlier to claim input tax credit. | ✕ No | ✓ Yes | ✓ Yes |
| 6 | MSME (Udyam) registration Registration of the LLP as a micro, small or medium enterprise under Udyam, filed after incorporation once the LLP has its certificate and PAN. It is part of the Silver and Gold packages, not Basic; mention it in your enquiry and we add it to the written estimate. | ✕ No | ✓ Yes | ✓ Yes |
| 7 | Shops Act registration Registration of the office under the shops and establishments law of its State, where that law applies to the premises. It is a State registration, separate from the MCA filings, and the rules and fees differ from State to State. The Silver and Gold packages include it. | ✕ No | ✓ Yes | ✓ Yes |
| 8 | Annual Return (Form 11) Form 11 is the LLP’s annual return, due within 60 days of the end of the financial year, that is by 30 May (Section 35; Rule 25). An LLP incorporated after 30 September may run its first financial year to the next 31 March, which moves the first Form 11 out by a year. | ✕ No | ✕ No | ✓ Yes |
| 9 | Accounts & Solvency (Form 8) Form 8 is the statement of account and solvency, signed by the designated partners and due within 30 days from the end of six months of the financial year, that is by 30 October. An LLP above the Rule 24(8) audit limits files its audited accounts with it. | ✕ No | ✕ No | ✓ Yes |
| 10 | LLP income-tax return The LLP files its own income-tax return as a firm under the Income-tax Act, 2025: by 31 August if its accounts are not audited, and by 31 October if they are audited under any law. Tax is 30% of total income, plus surcharge where it applies and 4% cess. | ✕ No | ✕ No | ✓ Yes |
| Choose a package | Basic | Silver | Gold |
← Swipe sideways to compare all packages →
Documents Required for LLP Registration
The Registrar checks every detail typed into FiLLiP against the attachments. So, a mismatch between the PAN name, the Aadhaar address, and the bank statement is the most common reason an LLP application is returned for resubmission. You need documents from every partner, extra papers where a partner is a company or a foreign national, and proof of the registered office. Everything is uploaded as scans; nothing goes on paper.
From every partner
-
PAN cardEvery Indian partner provides a PAN, and the name entered in FiLLiP must match the PAN database exactly. Correct any spelling difference before we start.
-
Aadhaar cardAadhaar is used for the partner’s e-KYC and for the one-time password that issues the digital signature, so keep the mobile number linked to it at hand during Step 1. Check that the Aadhaar address matches the address proof you send, as FiLLiP checks both.
-
Identity proofA passport, voter ID card, or driving licence as a second identity proof for each partner. FiLLiP attaches it for every designated partner who needs a DPIN. The name on it should match the PAN; a foreign partner gives the passport, listed separately below.
-
Address proof (latest)A bank statement or an electricity, telephone, or mobile bill in the partner’s name, not older than two months. FiLLiP attaches it as residence proof for each designated partner, and the address should match the Aadhaar address to avoid resubmission.
-
Passport-size photographA recent passport-size photograph of each partner on a plain background, in a readable digital format. It goes with the partner’s KYC papers. A scan of a printed photograph or a clear, front-facing phone photograph both work; it need not be a studio print.
-
Class 3 Digital SignatureEvery designated partner needs a Class 3 digital signature to sign FiLLiP and Form 3. A licensed Certifying Authority issues it after you complete video e-KYC under the Information Technology Act, 2000, on your phone. We arrange it in Step 1.
Foreign or corporate partners
-
Passport (foreigner or NRI)A foreign national or NRI partner gives a passport and a recent address proof. Notarise and apostille documents signed abroad, or consularise them where the country is not in the Hague Convention. At least one designated partner must still be resident in India.
-
Incorporation certificate (if applicable)If a company or another LLP is a partner, attach its certificate of incorporation and, if it is Indian, its PAN. A body corporate acts through an individual it nominates; a foreign one’s papers are apostilled or consularised like a foreign partner’s.
-
Board resolutionA resolution of the corporate partner’s board authorising its investment in the LLP and naming the individual who will act for it as designated partner. That individual then provides personal KYC and gets a digital signature like any other designated partner.
For the registered office
-
Utility bill of the premisesAn electricity, water, gas or telephone bill of the registered office premises, showing the full address and not older than two months.
-
NOC from the ownerWhere the premises are rented or belong to someone else, such as a family member, the owner signs an NOC permitting use as the registered office. A residential address can be used. FiLLiP takes the NOC with the utility bill. A ready format is linked.
-
Rent or lease agreementIf the premises are rented, a copy of the rent or lease agreement supports the owner’s NOC; FiLLiP lists it, along with rent receipts, as accepted proof of the office. The owner’s name on it should match the NOC and the utility bill.
Pro tip: an LLP cannot defer its registered office the way a company can. FiLLiP asks for the address and its proof at filing, so keep the utility bill and the owner’s NOC ready before Step 3.
Step-by-Step LLP Registration Process
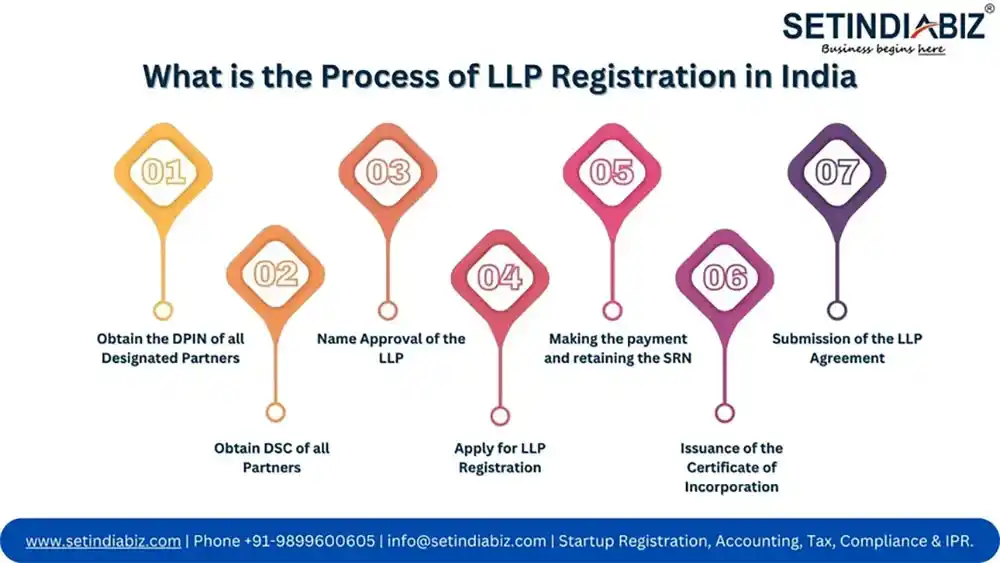
You file the entire application online on the MCA V3 portal; you don’t need to visit the Registrar’s office. The steps and MCA fees are the same in every State, whether the office is in Delhi, Mumbai, Bengaluru or Chennai; only the stamp duty and the jurisdictional ROC change. The six steps below cover the full route, assuming no partner yet has a digital signature or DPIN. The Central Registration Centre approves the name, and the Registrar of Companies in the State where the registered office is located registers the LLP.
-
Collect KYC and issue digital signatures
We collect each partner’s KYC and verify that names and addresses match across documents. A licensed Certifying Authority issues a Class 3 digital signature to each designated partner after video e-KYC under the
Information Technology Act, 2000; you do the video check on your phone.⏳ Turnaround: the signature is issued after video e-KYC is approved.
-
Reserve the LLP name through RUN-LLP
We run a name search on the MCA portal and the trade mark register, then file
RUN-LLPwith up to two proposed names and the ₹200 government fee. Once the Central Registration Centre approves a name, it reserves it for three months underRule 18, and you must file FiLLiP within that period. You shortlist the names in order of preference.⏳ Turnaround: CRC approval; a resubmission adds a further round.
-
Prepare the incorporation document
We prepare the incorporation document under
Section 11: the LLP’s name, business, registered office, the partners and designated partners, and each partner’s contribution, with the subscribers’ sheet, the designated partners’ consent and the statement by a practising professional thatSection 11(1)(c)requires. You review the details and sign with your DSC.⏳ Turnaround: drafting runs while the name is under approval.
-
File FiLLiP with the linked applications
Now we file
FiLLiPwith the registered office proof and the partners’ documents. The same filing allots DPINs to up to five designated partners who do not have one (Rule 11) and applies for the LLP’s PAN and TAN, so no separate DPIN, PAN or TAN application is needed.⏳ Turnaround: filed within the three-month name-reservation period.
-
ROC scrutiny and Certificate of Incorporation
The Registrar scrutinises the application; if it is marked for resubmission, we correct and refile within the time allowed.
Section 12directs the Registrar to register a complete filing within 14 days and issue the Certificate of Incorporation with the LLPIN; the certificate also carries the PAN and TAN.⏳ Turnaround: within 14 days of a complete filing under Section 12; a resubmission adds time.
-
Execute the LLP agreement and file Form 3
We draft the LLP agreement on contribution, profit sharing, duties and admission or exit of partners (
Section 23). The partners sign it on stamp paper of the value fixed by the State’s stamp law, and we file it inForm 3within 30 days of incorporation. Without a filed agreement, the default rules in the First Schedule govern the partners. With the certificate, PAN and filed agreement, the partners can then open a current account in the LLP’s name; the bank verifies the LLP’s legal existence and the partner authorised to act for it under paragraph 37 of the RBI (Commercial Banks – KYC) Directions, 2025, which covers juridical persons not named elsewhere in the Directions.⏳ Turnaround: Form 3 within 30 days of incorporation.
Timeline for LLP Registration
LLP registration typically takes 10–15 working days once documents are complete, and the LLP agreement is filed within 30 days after that. Stages overlap: drafting runs while the name is under approval.
-
Day 1–2
Digital Signature
We check every partner’s KYC and apply for a Class 3 DSC for each designated partner, issued after video e-KYC.
-
Day 2–4
Name Reservation
We file RUN-LLP with two proposed names; the approved name is reserved for three months under Rule 18.
-
Day 4–15
FiLLiP and Certificate
We file FiLLiP; under Section 12, the Registrar has 14 days to issue the Certificate of Incorporation with the LLPIN, PAN, and TAN.
-
Within 30 days
LLP Agreement
The partners sign the LLP agreement on stamp paper, and we file it in Form 3 within 30 days of incorporation.
Video Guide on LLP Registration
Watch how an LLP is registered in India: who can be a partner, why two designated partners are needed, what the Registrar checks in FiLLiP, and why the LLP agreement has to be filed within 30 days. The videos are hosted on YouTube and load only when you press play.
LLP registration in India — process, documents and agreement
Covers what an LLP is, the rule of two partners and two designated partners, with one resident in India, the DSC, DPIN, and KYC papers, and Forms 3, 8, and 11.
LLP registration process — the six steps
A walk-through of the six steps: digital signatures and DIN, choosing a name that meets MCA rules, the online incorporation forms, the LLP agreement and later filings.
LLP vs Private Limited Company vs Partnership Firm
Two or more founders usually shortlist these three structures, and the choice turns on whether outside investors will hold equity. An LLP and a private limited company are both separate legal persons with limited liability; the LLP trades the ability to issue shares for lighter meeting and audit rules. Under the Indian Partnership Act, 1932, a partnership firm is not a separate legal person, so every partner is liable for the firm’s debts.
| No. | Point of difference | LLP | Private Limited Company | Partnership Firm |
|---|---|---|---|---|
| 1 | Governing law | LLP Act, 2008 | Companies Act, 2013, Section 2(68) | Indian Partnership Act, 1932 |
| 2 | Registration | Compulsory, with the Registrar of Companies | Compulsory, with the Registrar of Companies | Optional, with the State Registrar of Firms |
| 3 | Legal status | Separate legal entity (Section 3) | Separate legal entity (Section 9) | Not separate from its partners |
| 4 | Liability | Limited to the agreed contribution (Section 28) | Limited to the unpaid amount on shares | Unlimited, joint and several |
| 5 | Owners | Minimum 2 partners, no maximum | 2 to 200 members | 2 to 50 partners |
| 6 | Management | Designated partners, under the LLP agreement | Board of directors, minimum 2 | Partners, under the partnership deed |
| 7 | Meetings | None required by law | Board meetings and an AGM every year | None required by law |
| 8 | Annual filings | Form 11 by 30 May; Form 8 by 30 October | AOC-4 and MGT-7/7A after the AGM | None with a registrar; income-tax return only |
| 9 | Statutory audit | Only above the Rule 24(8) limits | Every year (Section 139) | No statutory audit |
| 10 | Income tax | Taxed as a firm, 30% plus surcharge and cess | 22%, 25% or 30% plus surcharge and cess | Taxed as a firm, 30% plus surcharge and cess |
| 11 | Raising equity | No shares; investors come in as partners | Shares, preference shares and ESOPs | No shares to issue |
| 12 | Foreign investment | Automatic route in sectors open 100% without FDI-linked conditions | Automatic or approval route as per sector | Not open under the FDI automatic route |
| Quick Takeaway: Choose an LLP when two or more partners will run a services or trading business, want limited liability, and do not plan to sell equity to investors. Choose a private limited company when venture funding or ESOPs are likely; an LLP cannot issue shares. Stay a partnership firm only where limited liability does not matter to the partners. | ||||
← Swipe sideways to compare all structures →
Benefits of LLP Registration
Limited liability is the main reason, but many partners choose an LLP over a company because it gives corporate standing with lighter governance, run by an agreement instead of a board. The advantages below follow directly from the Limited Liability Partnership Act, 2008 and the LLP Rules, 2009 as they stand after the 2021 amendments.
Separate legal entity
The LLP owns property, holds bank accounts, signs contracts, and sues or is sued in its own name, and continues regardless of what happens to individual partners (Sections 3 and 14).
Limited liability
A partner is not personally liable for the LLP’s obligations merely by being a partner, and is not liable for another partner’s wrongful act (Sections 27 and 28).
Run by your own agreement
Partners agree on profit sharing, decision-making, and admission and exit of partners in the LLP agreement; there is no board and no prescribed meeting cycle (Section 23).
Lighter compliance
Two annual MCA filings, Form 11 and Form 8, and no statutory audit while turnover stays within ₹40 lakh or contribution within ₹25 lakh (Rule 24(8)).
Profits taxed once
The LLP pays tax on its income as a firm; a partner’s share of that profit is exempt in the partner’s hands, and there is no dividend to tax.
Open to foreign partners
Foreign nationals and foreign companies can be partners, and foreign investment comes in under the automatic route in sectors open 100% without FDI-linked conditions.
Government Fees for LLP Registration
The MCA fee for FiLLiP and for Form 3 depends on the total contribution in the incorporation document; RUN-LLP costs ₹200 regardless of the size. For a contribution up to ₹1 lakh, the three MCA fees total ₹750 (₹200 + ₹500 + ₹50). If the partners later raise the contribution into a higher slab, the LLP pays only the difference in the registration fee, through Form 3 (Annexure A, item 2). DSC charges and State stamp duty on the LLP agreement are paid separately at actuals.
| No. | Total contribution | FiLLiP fee | Form 3 fee |
|---|---|---|---|
| 1 | Up to ₹1 lakh | ₹500 | ₹50 |
| 2 | Above ₹1 lakh up to ₹5 lakh | ₹2,000 | ₹100 |
| 3 | Above ₹5 lakh up to ₹10 lakh | ₹4,000 | ₹150 |
| 4 | Above ₹10 lakh up to ₹25 lakh | ₹5,000 | ₹200 |
| 5 | Above ₹25 lakh up to ₹1 crore | ₹10,000 | ₹400 |
| 6 | Above ₹1 crore | ₹25,000 | ₹600 |
Stamp duty on the LLP agreement is a separate State charge, set out State by State in the next section.
State-wise Stamp Duty and Stamp Paper Value for an LLP Deed
In most States, an LLP agreement attracts the same stamp duty as a partnership deed under the Stamp Act of the State where it is signed. Karnataka and Rajasthan have a separate article for LLPs, and Maharashtra and Gujarat name LLPs in their partnership article; the other six States in the table have no LLP entry, and the partnership article is applied in practice. The stamp paper value therefore differs from State to State. Some States charge a flat amount; others charge a share of the capital the partners bring in, with a floor and a ceiling. The table shows the rule in ten States and the duty on cash capital of ₹1 lakh, ₹5 lakh, and ₹10 lakh. Where a partner brings in land or a building, several States, including Maharashtra, Gujarat and Rajasthan, charge the deed like a conveyance, and the duty is much higher.
| No. | State | Rule for Stamp Duty on LLP Agreement | ₹1 Lakh Capital | ₹5 Lakh Capital | ₹10 Lakh Capital |
|---|---|---|---|---|---|
| 1 | Maharashtra | ₹500 where cash capital is up to ₹50,000; above that, 1% of the whole capital, capped at ₹50,000 (Article 47, Schedule I, Maharashtra Stamp Act, 1958) | ₹1,000 | ₹5,000 | ₹10,000 |
| 2 | Delhi | 1% of capital, capped at ₹5,000, with no minimum (Article 46, Schedule I-A, Indian Stamp Act, 1899, as amended by Delhi) | ₹1,000 | ₹5,000 | ₹5,000 |
| 3 | Karnataka | ₹5,000 where the capital does not exceed ₹10 lakh (Article 40-A, Karnataka Stamp Act, 1957, a separate LLP article) | ₹5,000 | ₹5,000 | ₹5,000 |
| 4 | Tamil Nadu | ₹50 where capital is up to ₹500; ₹1,000 in any other case (Article 46, Schedule I, Indian Stamp Act, 1899, as amended by Tamil Nadu Act 13 of 2024) | ₹1,000 | ₹1,000 | ₹1,000 |
| 5 | Gujarat | ₹1 for every ₹100 of capital or part of it, capped at ₹10,000 (Article 44, Schedule I, Gujarat Stamp Act, 1958) | ₹1,000 | ₹5,000 | ₹10,000 |
| 6 | Uttar Pradesh | ₹40 per ₹1,000 where capital is up to ₹10,000; in any other case, the duty on a bond for ₹10,000, which the department charges at ₹400 (Article 46, Schedule I-B, Indian Stamp Act, 1899, as amended by Uttar Pradesh) | ₹400 | ₹400 | ₹400 |
| 7 | Telangana | ₹100 where capital is up to ₹5,000; ₹500 in any other case (Article 41-A, Schedule I-A, Indian Stamp Act, 1899, as applied in Telangana) | ₹500 | ₹500 | ₹500 |
| 8 | West Bengal | ₹20 where capital is up to ₹500, ₹50 up to ₹10,000, ₹100 up to ₹50,000 and ₹150 above that (Article 46, Schedule IA, Indian Stamp Act, 1899, as amended by West Bengal) | ₹150 | ₹150 | ₹150 |
| 9 | Rajasthan | ₹2,000 for every ₹50,000 of cash capital or part of it, capped at ₹10,000, plus a 30% surcharge under Sections 3-A and 3-B, so ₹5,200, ₹13,000 and ₹13,000 in all (Article 35-B, Rajasthan Stamp Act, 1998, a separate LLP article) | ₹4,000 | ₹10,000 | ₹10,000 |
| 10 | Madhya Pradesh | Flat ₹5,000 where cash capital is up to ₹50,000; above that, 2% of capital, minimum ₹2,000 and maximum ₹10,000 (Article 49, Schedule I-A, Indian Stamp Act, 1899, as amended by Madhya Pradesh) | ₹2,000 | ₹10,000 | ₹10,000 |
These figures are for cash capital and leave out e-stamping or franking charges; for Rajasthan, the amounts are before the surcharge shown in the rule. States revise rates by notification, so we confirm your State’s current rate in the written estimate before printing the deed. We draft the LLP agreement and file it in Form 3; you buy the stamp paper or e-stamp and arrange any notarisation, at your own cost.
Annual Compliance and Tax for an LLP
Registration starts the LLP’s compliance year. The calendar below lists what an LLP files, when, and under which provision; a late Form 11 or Form 8 attracts an additional fee of 1 to 15 times the normal fee for a small LLP (1 to 30 times for others) up to 360 days, plus ₹10 a day (₹20 for others) after that, so Setindiabiz tracks the dates for the LLPs it registers. The table after it shows how an LLP is taxed.
| No. | Filing | Form | Due date | Legal basis |
|---|---|---|---|---|
| 1 | LLP agreement | Form 3 | Within 30 days of incorporation, and of every change | Section 23(2); Rule 21 |
| 2 | Change in partners | Form 4 | Within 30 days of the admission or exit | Section 25(2) |
| 3 | Annual return | Form 11 | Within 60 days of the financial year end (by 30 May) | Section 35; Rule 25 |
| 4 | Statement of account and solvency | Form 8 | Within 30 days from the end of six months of the financial year (by 30 October) | Section 34(3); Rule 24(4) |
| 5 | Audit of accounts | Auditor’s report | Every year, unless turnover is within ₹40 lakh or contribution within ₹25 lakh | Section 34(4); Rule 24(8) |
| 6 | Income-tax return | Firm’s return | 31 August if the accounts are not audited; 31 October if audited under any law | Section 263(1), Income-tax Act, 2025, as amended by the Finance Act, 2026 |
| 7 | Designated partner KYC | DIR-3-KYC-Web | Once every third financial year, by 30 June | Rule 12A, Companies (Appointment and Qualification of Directors) Rules, 2014 (a DPIN is now a DIN) |
← Swipe sideways to see all columns →
How an LLP is taxed
From 1 April 2026, the Income-tax Act, 2025 applies, and it treats an LLP as a firm (Section 2(45)). The LLP pays tax on its own income; the partners do not pay again on their share.
| No. | Item | Rate or rule | Where it is written |
|---|---|---|---|
| 1 | Income tax | 30% of total income | Finance Act, 2026, First Schedule, Paragraph C |
| 2 | Surcharge | 12% of tax where total income exceeds ₹1 crore | Finance Act, 2026, First Schedule, Paragraph F |
| 3 | Health and education cess | 4% of tax plus surcharge | Finance Act, 2026 |
| 4 | Alternate minimum tax | 18.5% of adjusted total income, only where specified deductions are claimed | Section 206(2), Income-tax Act, 2025 |
| 5 | Partner’s share of profit | Exempt in the partner’s hands | Schedule III, Sl. No. 2, Income-tax Act, 2025 |
| 6 | Remuneration and interest to partners | Deductible for working partners if the agreement provides; interest up to 12% a year; remuneration up to the higher of ₹3 lakh or 90% of the first ₹6 lakh of book profit, plus 60% of the balance | Section 35(e), Income-tax Act, 2025 |
| 7 | Presumptive taxation | Not available to an LLP | Section 58, Income-tax Act, 2025 |
Further Reading — Expert Resources on LLPs
Company vs LLP vs OPC: which structure is right in 2026?
Compare owners, liability, audit, funding and yearly filings of each structure and pick the one that fits your plan.
LLP defined: features of limited liability partnerships
The meaning and key features of an LLP, from limited liability to the partners’ agreement.
Step-by-step registration process of an LLP
The registration route from DSC and name approval to FiLLiP and the LLP agreement.
LLP registration documents in India
Partner identification, address proofs, office documents and the incorporation forms, with draft formats.
Advantages and disadvantages of an LLP
What an LLP offers over a partnership firm, and where a company still fits better.
Small LLP: meaning, definition and legal basis
Section 2(1)(ta) of the LLP Act: contribution and turnover limits, and the lighter fees that follow.
Frequently Asked Questions
Each answer includes the section, rule, or form number so that you can verify the position on mca.gov.in or India Code.
An LLP is a body corporate formed and incorporated under the Limited Liability Partnership Act, 2008 (Section 2(1)(n)). It is a legal entity separate from its partners, with perpetual succession (Section 3), so changes in partners do not end it. The LLP agreement sets the partners’ mutual rights and duties, or the First Schedule applies where the agreement is silent (Section 23).
A firm under the Indian Partnership Act, 1932 is not a separate legal person: its partners are jointly and severally liable for its debts without limit, and registration of the firm is optional. An LLP must be registered with the Registrar of Companies, owns property in its own name, and a partner is not personally liable for its obligations merely by being a partner (Section 28, LLP Act, 2008). An existing firm can convert into an LLP under Section 55 and the Second Schedule by filing Form 17.
Both are separate legal entities with limited liability. A company has a board, holds board meetings and an AGM, and must have its accounts audited every year (Section 139, Companies Act, 2013). An LLP is run under its agreement, has no prescribed meetings, and needs an audit only above the limits in Rule 24(8) of the LLP Rules, 2009. A company can issue shares and ESOPs, but an LLP cannot, so equity investors usually prefer a private limited company.
A small LLP is one whose partners’ contribution does not exceed ₹25 lakh and whose turnover for the immediately preceding financial year does not exceed ₹40 lakh, both conditions together; the Government may raise the limits by rules, up to ₹5 crore and ₹50 crore (Section 2(1)(ta), LLP Act, 2008, inserted by the LLP (Amendment) Act, 2021). A small LLP pays lower filing fees and lower additional fees for delay. See the small LLP entry for the details.
Yes. As a body corporate, an LLP can acquire, own, hold, and dispose of property; sue and be sued; and do anything a body corporate may lawfully do, all in its own name (Section 14, LLP Act, 2008). Its bank account, GST registration and licences are in the LLP’s name, not the partners’.
At least two (Section 6(1), LLP Act, 2008); there is no maximum. If the number falls below two and the LLP carries on business for more than six months with one partner, that partner is personally liable for the obligations incurred during that period, if they know they are the sole partner (Section 6(2)).
Any individual or body corporate (Section 5, LLP Act, 2008), including a foreign national, an NRI, an Indian or foreign company, or another LLP. An individual of unsound mind, an undischarged insolvent, or one who has applied to be adjudicated insolvent cannot be a partner. A body corporate acts through an individual it nominates.
Designated partners are the partners responsible for the LLP’s compliance, including filings, registers, and penalties (Section 8, LLP Act, 2008). Every LLP needs at least two, both individuals, and at least one must be resident in India, that is, have stayed in India for not less than 120 days during the financial year (Section 7(1) and its Explanation, as amended by the LLP (Amendment) Act, 2021). Each designated partner needs a DPIN and a digital signature.
Yes. A foreign national or foreign company can be a partner, but at least one designated partner must be resident in India. Foreign investment in an LLP is allowed under the automatic route in sectors where 100% FDI is allowed under the automatic route, and no FDI-linked performance conditions apply (Foreign Exchange Management (Non-debt Instruments) Rules, 2019). Citizens and entities of Pakistan and Bangladesh are excluded, and investors from other countries sharing a land border with India need specific advice before contributing.
Yes, as the LLP agreement provides. The LLP files Form 4 with the Registrar within 30 days of a partner’s admission or exit, or of a change in a partner’s name or address (Section 25, LLP Act, 2008), and Form 3 within 30 days where the agreement itself changes.
In two filings on the MCA V3 portal: RUN-LLP to reserve the name (Rule 18, LLP Rules, 2009) and FiLLiP to incorporate the LLP (Section 11 and Rule 11). FiLLiP carries the incorporation document, the partners’ details and contributions, proof of the registered office, and the designated partners’ consent; it also allots DPINs to up to five individuals and applies for PAN and TAN. A practising advocate, company secretary, chartered accountant or cost accountant certifies it (Section 11(1)(c)). The Registrar then issues the Certificate of Incorporation under Section 12.
FiLLiP, the Form for incorporation of Limited Liability Partnership, is the integrated web form on the MCA V3 portal for incorporating an LLP. It can reserve the name if RUN-LLP was not filed, allots DPINs to designated partners who do not have one, and applies for the LLP’s PAN and TAN, all in one application.
A Designated Partner Identification Number, which every designated partner must hold (Section 7(6), LLP Act, 2008; Rule 10, LLP Rules, 2009). A person who already has a DIN as a company director uses the DIN as the DPIN. New designated partners get the DPIN through FiLLiP, so they don’t need a separate application at incorporation.
Typically 10–15 working days from the time documents are complete: one to two days for the digital signatures, two to four for RUN-LLP name approval, and the balance for FiLLiP and the Registrar’s approval. Section 12 gives the Registrar 14 days to register a complete filing. A resubmission adds a further round. The LLP agreement is then filed in Form 3 within 30 days of incorporation (Rule 21, LLP Rules, 2009).
RUN-LLP costs ₹200. The FiLLiP fee and the Form 3 fee depend on the partners’ contribution, from ₹500 and ₹50 for a contribution up to ₹1 lakh to ₹25,000 and ₹600 above ₹1 crore (Annexure A, LLP Rules, 2009, from 1 April 2022); the full slab table is under Government Fees on this page. State stamp duty on the LLP agreement and the DSC charges are paid at actuals. At the lowest slab, the MCA fees total ₹750. No minimum capital is required; partners can start with any contribution they agree on.
It is the written agreement among the partners, or between the LLP and its partners, on contribution, profit sharing, management, admission and exit (Section 2(1)(o) and Section 23, LLP Act, 2008). If the agreement is silent on a point, the default rules in the First Schedule apply; for example, all partners share profits and contribute equally.
File the initial LLP agreement in Form 3 within 30 days of incorporation, and file every change within 30 days of the change (Section 23(2); Rule 21, LLP Rules, 2009). A late Form 3 can still be filed with an additional fee that is a multiple of the normal fee: one time up to 15 days, then 2 times for a small LLP and 4 times for others up to 30 days, rising to 25 and 50 times beyond 360 days (Annexure A, item 8, LLP Rules, 2009, from 1 April 2022).
Yes. The agreement is executed on stamp paper, or e-stamped, at the value fixed by the stamp law of the State where it is signed, which in most States depends on the contribution. The stamped and signed agreement is what is attached to Form 3. We tell you the exact duty for your State in the written estimate.
Form 11, the annual return, within 60 days of the end of the financial year (by 30 May; Section 35; Rule 25), and Form 8, the statement of account and solvency, by 30 October (Section 34(3); Rule 24(4)). A late Form 11 or Form 8 pays an additional fee that rises with the delay, from 1 times the normal fee up to 15 days to 15 times (30 times for an LLP that is not small) up to 360 days, plus ₹10 a day (₹20) beyond that (Annexure A, LLP Rules, 2009, from 1 April 2022). It also files its income-tax return, and each designated partner completes DIR-3 KYC once every third financial year. See LLP annual compliance for the full calendar.
Section 34(4) of the LLP Act, 2008 requires an audit as prescribed, and Rule 24(8) of the LLP Rules, 2009 exempts an LLP whose turnover in the financial year does not exceed ₹40 lakh or whose contribution does not exceed ₹25 lakh. An LLP outside that exemption appoints an auditor and files the audited accounts with Form 8. A tax audit under the Income-tax Act, 2025 is a separate test.
From 1 April 2026, the Income-tax Act, 2025 treats an LLP as a firm (Section 2(45)). It pays 30% on its total income (Finance Act, 2026, First Schedule, Paragraph C), plus a 12% surcharge where income exceeds ₹1 crore and 4% health and education cess. A partner’s share of the LLP’s profit is exempt in the partner’s hands (Schedule III, Sl. No. 2), and remuneration and interest paid to working partners are deductible within the limits of Section 35(e). Alternate minimum tax at 18.5% applies only if the LLP claims specified deductions (Section 206(2)), and neither presumptive scheme in Section 58 is open to an LLP.
Yes. A partnership firm converts under Section 55 and the Second Schedule of the LLP Act, 2008 by filing Form 17 with FiLLiP, and a private company or an unlisted public company under Section 56 or 57 and the Third or Fourth Schedule by filing Form 18 with FiLLiP. The conversion pays the same registration fee slabs as a new LLP (Annexure A, LLP Rules, 2009).
Only when the law requires it: when aggregate turnover crosses the registration threshold (₹20 lakh for services, or ₹10 lakh in Manipur, Mizoram, Nagaland and Tripura; ₹40 lakh for a supplier of goods only, except in the States listed in Notification No. 10/2019-Central Tax), or from the first sale for inter-State taxable supply of goods or supply through an e-commerce operator (Sections 22 to 24, CGST Act, 2017). GST is not part of LLP incorporation. An LLP can register voluntarily to claim input tax credit. See GST registration.
Four things, mostly in the first month. File the LLP agreement in Form 3 within 30 days of incorporation if it is not already on record (Rule 21, LLP Rules, 2009). Open a current account in the LLP’s name with the Certificate of Incorporation, PAN and the LLP agreement, and bring in each partner’s contribution as agreed. The bank verifies the LLP’s legal existence and the partner authorised to act for it under paragraph 37 of the RBI (Commercial Banks – KYC) Directions, 2025, which covers juridical persons not named elsewhere in the Directions. The LLP must show its name, registered office address, registration number, and a statement that it is registered as a limited liability entity on its invoices, letters, and other official papers (Section 21, LLP Act, 2008). Then register under GST where the threshold or a compulsory category applies (Sections 22 and 24, CGST Act, 2017), and under the State shops and establishments law for the office. Unlike a company, an LLP does not file a commencement-of-business declaration.
No questions in this category yet. Choose another category or select “All”.
Request a Call / Quote
Send us your requirements, and you will receive a written estimate showing the professional fee, statutory fees, and GST as separate heads, along with the scope, the documents we will need, a working-day timeline for each step, and any exclusions. No payment is taken before you have read it.
Written estimate first
Fee, statutory charges and GST shown separately, upfront.
Free consultation
A process expert explains the scope and options. No obligation.
Quality you can check
Defined deliverables; qualified professionals where required.
Support through completion
One point of contact, status updates and a support portal.
Clear scope and timeline
Documents needed, working-day timeline, exclusions listed.
Online, across India
Online delivery from Noida, Mumbai, Bengaluru, Hyderabad.
📞 +91 98996 00605 📧 help@setindiabiz.com
🕒 Mon–Sat · 9:30 AM – 6:30 PM Details used only for your estimate — privacy policy.
