
Overview: A Partnership Deed records the agreement between business partners and sets out how the firm will operate. It covers capital contributions, profit sharing, management powers, remuneration, partner exits and dispute resolution. A clear deed also supports income tax assessment and Registrar of Firms (ROF) registration. Partners should settle these terms before starting business and applying for statutory registrations.
Starting a business with a friend, family member or business associate often begins with mutual trust. However, disagreements over money, responsibilities or business decisions can create serious problems if the partners have not agreed on clear terms.
Without a written Partnership Deed, the default provisions of the Indian Partnership Act, 1932, may apply, even if those provisions are inconsistent with the partners’ original understanding. Lack of clarity in partnership arrangements can also affect tax deductions, retirement settlements and the recovery of business dues.
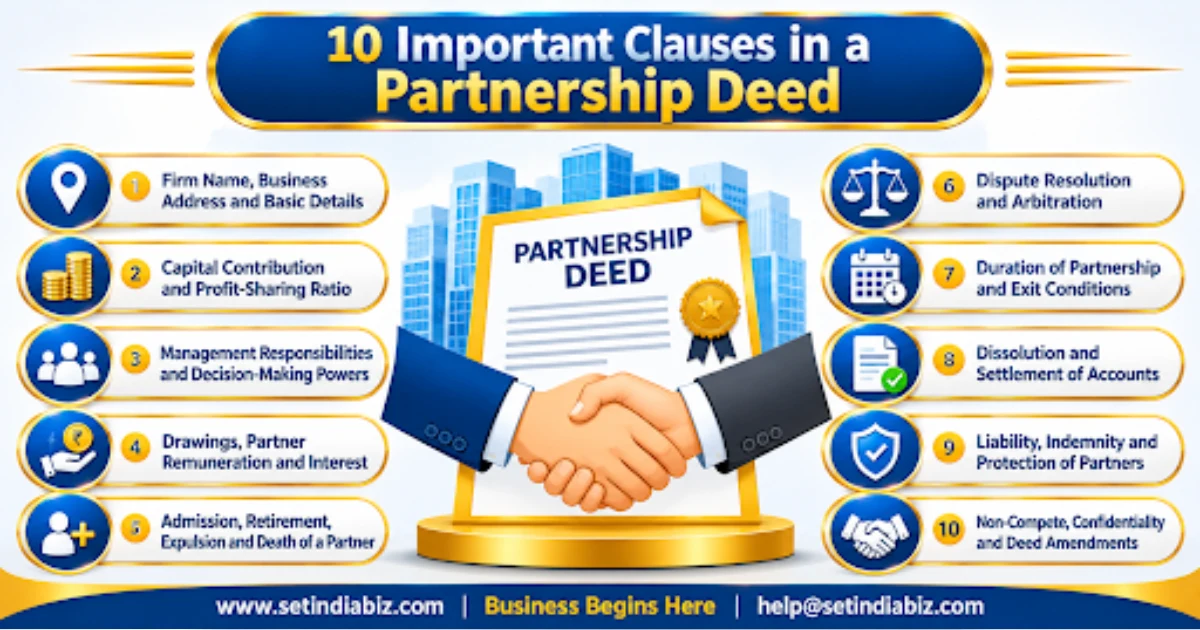
A well-drafted deed records the partners’ understanding and provides a framework for running the firm. Here are ten important clauses to consider before registering a partnership firm in India.
Watch
10 Important Clauses in a Partnership Deed
1. Firm Name, Business Address and Basic Details
The deed should record:
- Proposed firm name and nature of business.
- Principal place of business and branch addresses, if any.
- Full names and permanent addresses of all partners.
- Date of commencement and the date each partner joins.
- Duration of the partnership, whether fixed or at will.
Legal reference: Section 58 of the Indian Partnership Act, 1932.
Section 58(3) restricts firm names containing words such as ‘Crown’, ‘Emperor’, ‘Empire’, ‘King’, ‘Queen’ and ‘Royal’, or expressions implying Government approval or patronage, unless the State Government gives written consent.
Keep the firm’s name and particulars consistent across the Partnership Deed, PAN application, bank account documents and ROF registration application.
2. Capital Contribution and Profit-Sharing Ratio
Capital contribution and profit-sharing ratios need not be the same. For example, one partner may contribute 70% of the capital while the partners agree to share profits equally.
Under Section 13(b) of the Partnership Act, partners share profits and losses equally by default, unless they agree otherwise.
Tax reference: Section 325 of the Income-Tax Act 2025
Section 325 requires a partnership to be supported by a written instrument that specifies each partner’s individual share to qualify for assessment as a firm.
A certified copy of the instrument must be filed with the return for the first tax year in which the firm seeks this status. If the firm’s constitution or the partners’ shares change, a certified copy of the revised instrument must be filed with the income tax return (ITR) for the relevant tax year.
Non-compliance can lead to disallowance of deductions for payments such as partner interest and remuneration under Section 326.
The deed should specify initial capital, additional contributions, withdrawal conditions and individual profit-and-loss shares.
3. Management Responsibilities and Decision-Making Powers
Partners should agree on who will manage daily operations and who can approve major business decisions.
Under Section 12(c) of the Partnership Act, ordinary business matters may be decided by a majority of partners, after every partner has had an opportunity to express an opinion. However, changing the nature of the firm’s business requires the consent of all partners.
The deed should define:
- Individual roles and management responsibilities.
- Voting rights and approval limits.
- Authority for borrowing, major purchases and contracts.
- Bank signatories and access to financial records.
4. Drawings, Partner Remuneration and Interest
Partners should agree on how they can withdraw money and whether working partners will receive remuneration.
Under Section 13 of the Partnership Act, a partner is not automatically entitled to remuneration for participating in the business. Interest on capital is payable only out of profits under the default rule. A partner making an additional business payment or advance beyond the agreed capital is entitled to 6% annual interest by default, unless the partners agree otherwise.
Tax treatment under Section 35(e) of the Income-tax Act 2025
For claiming business deductions:
- Remuneration paid to non-working partners cannot be claimed as a deduction when calculating the firm’s taxable business income.
- Remuneration to working partners and interest paid to partners must be authorised by the applicable Partnership Deed.
- The maximum remuneration deductible for working partners is calculated as follows:
– On the first ₹6 lakh of book profit, or where the firm makes a loss, ₹3 lakh or 90% of the book profit, whichever is higher.
– On the remaining book profit, 60%. - Interest exceeding 12% simple interest per annum is not deductible.
These tax deduction limits do not prevent partners from agreeing to different payment terms, although the excess may not qualify as a business deduction.
The Partnership Deed must authorise the payment of remuneration and interest for it to qualify for a tax deduction. Section 35(e) does not allow a deduction for payments relating to a period before the deed authorised them or for payments not permitted under the earlier deed.
The deed should specify drawings, remuneration, interest rates and payment conditions.
5. Admission, Retirement, Expulsion and Death of a Partner
The deed should explain how the firm will handle changes in its partnership.
The relevant provisions include:
- Section 31: Admission of a new partner generally requires the consent of all existing partners, subject to the agreement.
- Section 32: A partner may retire with the consent of the other partners, under an express agreement or by written notice where the partnership is at will.
- Section 33: Expulsion is permitted only when the deed grants that power and it is exercised in good faith.
- Section 42: The death of a partner can dissolve the firm unless the partners have agreed otherwise.
Include a continuity clause allowing the remaining partners to carry on the business after a partner’s death or retirement. Also specify how the outgoing or deceased partner’s share, goodwill and outstanding amounts will be valued and settled. Legal heirs do not automatically become partners; their admission must follow the agreement and Section 31.
For a registered firm, public notice of retirement must follow Section 72. This includes notice to the Registrar under Section 63 and publication in the Official Gazette and at least one vernacular newspaper circulating in the relevant district.
Under Section 32, a retiring partner remains liable for debts arising from acts of the firm before retirement unless the partner is discharged through an agreement with the creditors and the partners of the reconstituted firm. Public notice is also important because liability to third parties for acts of the firm after retirement may continue until such notice is given.
6. Dispute Resolution and Arbitration
The deed should provide a clear process for resolving disagreements over accounts, management, profit distribution or other business matters.
Section 7 of the Arbitration and Conciliation Act, 1996, recognises a written arbitration agreement, including an arbitration clause in a contract.
Partners may provide for negotiation or mediation before arbitration. The clause should also specify the seat of arbitration, language, number of arbitrators and appointment procedure.
7. Duration of Partnership and Exit Conditions
The deed should state whether the firm is established for a fixed period, a particular project or an indefinite period.
Under Section 7 of the Partnership Act, a partnership is at will when the agreement makes no provision for its duration or determination. Section 8 recognises a partnership formed for a particular adventure or undertaking.
Under Section 43, any partner may dissolve a partnership at will by giving written notice to all other partners. For a fixed-term partnership, the agreed exit and dissolution conditions should be recorded clearly.
Specify the notice period, service of notice, retirement procedure, handover responsibilities and settlement timeline.
8. Dissolution and Settlement of Accounts
The deed should explain how the firm’s assets and liabilities will be settled if the partners decide to close the business.
Section 48 of the Partnership Act provides the default order of settlement, subject to the partners’ agreement:
- Payment of debts owed to third parties.
- Repayment of partner advances beyond capital.
- Return of partners’ capital balances.
- Distribution of the remaining surplus according to profit-sharing ratios.
Losses are first met from profits, then from capital and, if necessary, by the partners individually in the proportions in which they share profits.
The deed should also cover asset valuation, goodwill, inventory, outstanding liabilities and preparation of final accounts.
9. Liability, Indemnity and Protection of Partners
Section 25 of the Partnership Act makes every partner jointly and severally liable for acts of the firm committed while they are a partner.
This means a creditor may seek recovery of the firm’s entire recoverable debt from one partner, even if that partner has a smaller profit-sharing ratio.
The deed should include internal indemnity provisions for losses caused by fraud, unauthorised borrowing, wilful misconduct or breach of agreed responsibilities. However, an indemnity clause cannot remove a third party’s statutory rights against the partners.
For a comparison of liability structures, see our article on LLP vs Partnership Firm.
10. Non-Compete, Confidentiality and Deed Amendments
Partners should agree on how business information, intellectual property, customer details and commercial interests will be protected.
Under Section 11(2) of the Partnership Act, partners may agree that a partner will not carry on another business while remaining in the firm. Section 36(2) permits an outgoing partner to agree to reasonable restrictions on carrying on a similar business after leaving, within specified local limits or for a specified period.
Section 11(1) provides that changes to the partners’ mutual rights and duties require the consent of all partners.
Include confidentiality obligations, reasonable non-compete terms and a written procedure for amending the deed. Important changes should be recorded through a supplementary deed signed by all partners.
Stamping, Signing and ROF Registration
After finalising the terms, the Partnership Deed must be executed on appropriate non-judicial stamp paper or through the prescribed e-stamping process, as applicable under the relevant State Stamp Act. Stamp duty varies between states.
All partners should sign the deed and retain executed copies. The firm can then apply for registration with the Registrar of Firms under Section 58. Registration is completed when the Registrar records the firm’s particulars under Section 59, subject to the applicable state procedure.
Registration is not generally compulsory for the existence of a partnership under the central Act. However, Section 69 restricts an unregistered firm from filing certain suits to enforce contractual rights against third parties. Section 69(1) also restricts a partner from filing a suit against the firm or another partner to enforce a right arising from a contract or conferred by the Partnership Act itself.
The restrictions extend to claims of set-off and other proceedings to enforce contractual rights. The Act preserves certain proceedings, including those for dissolution, accounts of a dissolved firm and recovery of its property.
ROF registration is therefore strongly advisable, particularly for firms that may need to enforce contractual rights or recover outstanding payments from customers and vendors.
Setindiabiz Support
Setindiabiz assists businesses with Partnership Deed drafting and the registration process, including:
- Drafting the deed around agreed capital, profit-sharing and management arrangements.
- State-specific stamp duty verification and execution guidance.
- Registrar of Firms registration.
- Partnership PAN and bank account documentation.
- GST registration and business tax compliance setup.
Contact Setindiabiz Executive for assistance with Partnership Deed drafting and Partnership Firm Registration in India.
FAQs
Yes. Partners can contribute different amounts of capital and agree to share profits and losses in different proportions. The deed should clearly record these arrangements.
Under Section 13(a) of the Partnership Act, a partner is not automatically entitled to remuneration. For a business deduction, Section 35(e) of the Income-tax Act 2025 requires remuneration to be authorised by the applicable deed, payable to working partners and within the prescribed limits.
Under Section 42(c) of the Partnership Act, the death of a partner can dissolve the firm unless the partners have agreed otherwise. A continuity clause allows the remaining partners to continue the business.
No. Registration is not generally compulsory for the existence of a partnership. However, Section 69 restricts unregistered firms and their partners from enforcing certain rights through court proceedings even as they can be sued in the court. Registration is strongly advisable.
A Partnership Deed should reflect the actual understanding between partners rather than rely on a standard template. Setting out clear commercial and governance terms at the outset can prevent costly disputes as the business grows.
Executing the deed correctly and registering the firm with the ROF also supports its legal and tax compliance.
